
 Contact
 How to shop

Delivery
Shopping guide
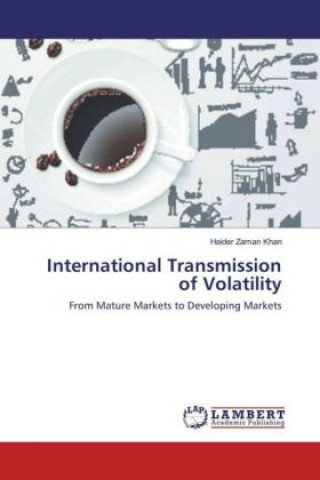
International Transmission of Volatility
From Mature Markets to Developing Markets
 English
 78 b
Up to 30 days for returns
Customers also purchased


 /
 Paperback
 20.68
€


 /
Paperback
25.50
€


 /
Paperback
60.55
€

The study tries to examine the mature market's (DAX, LSE, NIKKEI, NYSE, SSE) volatility transmission to developing market(s) (KSE). A ten year's (2005-2015) daily, weekly and monthly index returns of these markets are investigated under this study on which three econometric tests i.e. ADF (unit root), Chow and GARCH model are run to explore and analyze the stationarity, structural breaks and volatility effect from mature markets to volatile market(s) respectively. Results were found to be significant for all the observations, hence showing a transfer of volatility from all the mature markets under study i.e. DAX, LSE, NIKKEI, NYSE and SEE, to the volatile market which in this case is KSE. All the tests are run in econometric software EViews where GARCH model is used as the basic tool for analysis with support of ADF (unit root) and Chow test.


About the book
English

Give this book today
It's easy
1 Add to cart and choose Deliver as present at the checkout 2 We'll send you a voucher 3 The book will arrive at the recipient's addressYou might also be interested in

 /
Paperback
67.88
€


 /
Paperback
20.68
€
 /
 Adobe ePub DRM
113.82
€
 /
Adobe ePub DRM
73.44
€
 /
Paperback
28.81
€
Hi! I'm Libroamiko, your book advisor.
How can I help you?